Kemetic Minds — Financial Justice Series | June 24, 2026
💸 Key Findings
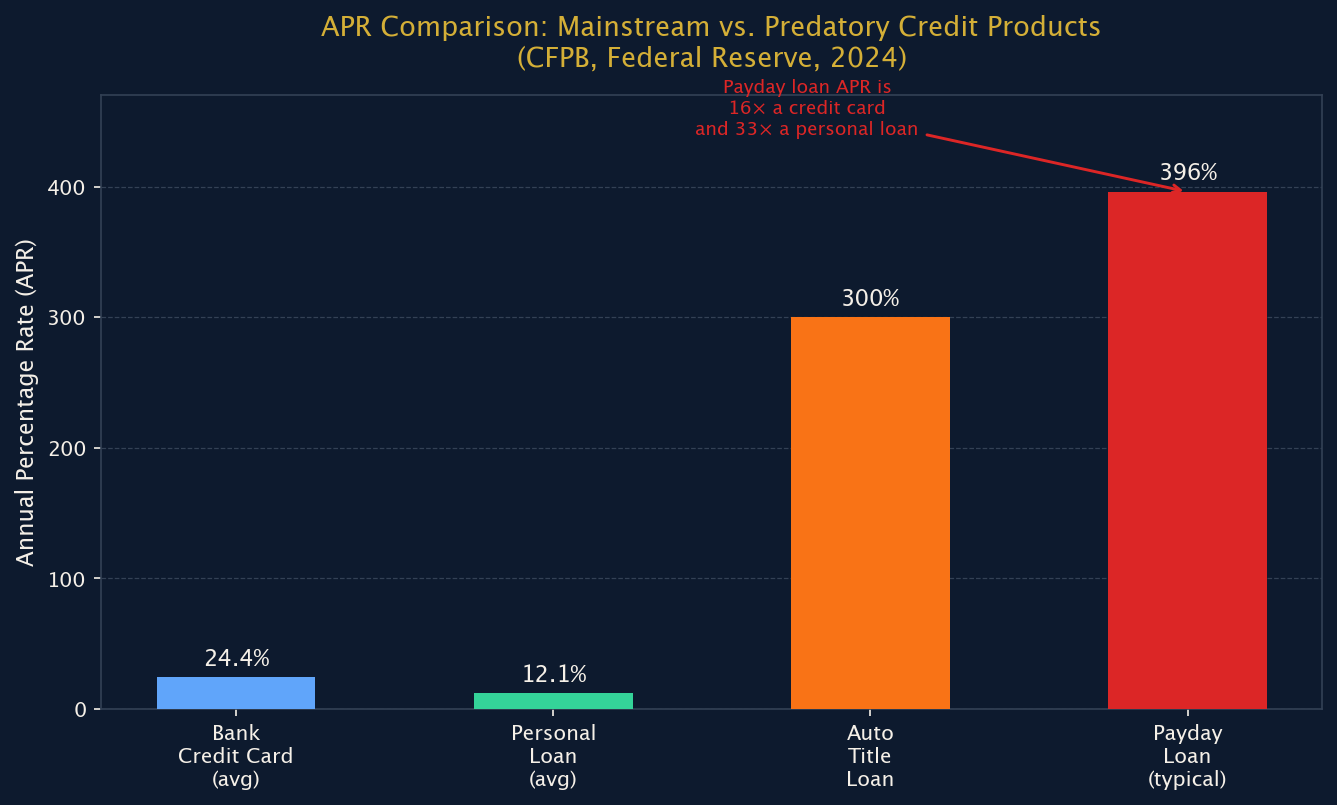
- A typical payday loan carries an APR of ~396% — 16× a credit card and 33× a personal loan (CFPB, 2024).
- Black Americans use payday and high-cost loans at higher rates than white Americans at every income level (FDIC, 2022).
- The payday lending industry extracts an estimated $9 billion per year from borrowers — the majority in fees, not principal repayment (Center for Responsible Lending, 2023).
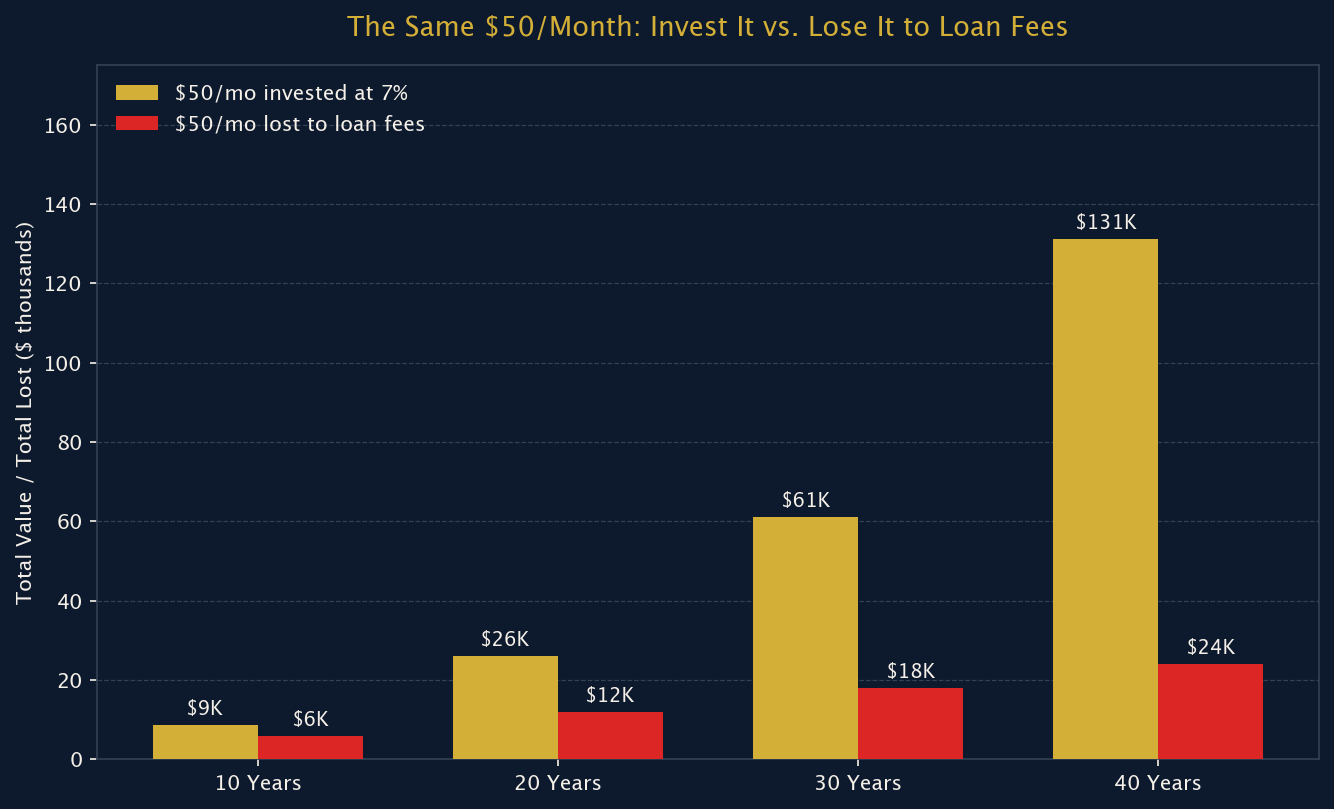
- That same $50/month redirected to a diversified index fund grows to $61,000 in 30 years at 7% annual return.
The Math That Changes Everything
A payday loan works like this: you borrow $300 for two weeks to cover a bill. The fee is $15 per
$100 borrowed — so $45 in fees. Two weeks later, you owe $345. If you cannot pay in full,
you roll it over for another two-week period and another $45 fee. After just four rollovers, you
have paid $180 in fees on a $300 loan and still owe the original $300.
Expressed as an annual percentage rate (APR), that $45 fee on a $300 2-week loan equals
391% APR. The Consumer Financial Protection Bureau (CFPB) found that the
typical payday loan is rolled over eight times — meaning the average
borrower pays $520 in fees to borrow $375 (CFPB, 2024).
Figure 1
APR Comparison: Mainstream vs. Predatory Credit Products
Who Pays the Most
The payday loan industry is not randomly distributed across the American population.
The FDIC’s 2021 national survey found that Black households use payday loans at
significantly higher rates than white households at every income level. This is not
explained by income differences alone. Research from the Center for Responsible Lending finds
that payday lenders concentrate their storefronts in majority-Black neighborhoods
at a disproportionate rate compared to similarly-income-matched white neighborhoods (CRL, 2023).
A 2023 CFPB report on consumer credit markets found that high-cost lenders including payday,
auto title, and rent-to-own companies extract $9 billion per year in fees from
borrowers — the large majority of which is renewal and rollover fees, not the original
credit itself. This is by design: the product is engineered for repeat borrowing.
The Opportunity Cost: What Those Fees Would Grow To
The most powerful way to understand predatory lending is through its opportunity cost —
what the same money would have become if redirected into an investment.
The average payday borrower pays approximately $520 in fees on a typical $375 loan cycle.
Annualized, the Center for Responsible Lending estimates the typical repeat borrower pays an average
of about $600 per year in payday loan fees — or about $50 per month.
Figure 2
The Opportunity Cost: $50/Month Invested vs. Lost to Loan Fees
$50 per month invested in a broad-market S&P 500 index fund at the historical average
return of approximately 10% grows to:
- 10 years: $10,235
- 20 years: $37,935
- 30 years: $112,920
- 40 years: $316,000
At the more conservative 7% (accounting for inflation), it still grows to
$61,000 over 30 years. The payday loan cycle does not just cost fees — it costs
decades of compound growth that belongs to the borrower’s future.
Alternatives to Payday Loans
Breaking the payday loan cycle requires both systemic change and individual alternatives.
Here are real options available right now:
🏦 Credit Union Payday Alternative Loans (PALs)
The National Credit Union Administration authorizes federal credit unions to offer Payday Alternative Loans (PALs): $200–$1,000, 1–6 month terms, maximum APR of 28%. This is the closest equivalent to a payday loan with dramatically lower costs. Find a credit union near you at MyCreditUnion.gov (NCUA, 2024).
💳 Employer Advance Programs
Apps like DailyPay, Earned Wage Access, and employer EWA programs allow you to access your earned wages before payday for a flat fee of $1–$3. This is not a loan — it is your own money — and carries no interest. Ask your HR department if your employer participates.
🤝 Community Organizations & Emergency Funds
The federal Low Income Home Energy Assistance Program (LIHEAP), local community action agencies, and mutual aid networks often provide emergency cash assistance, bill payment, and utility support without interest. Call 211 for local referrals — it is free and confidential.
📱 CDFI Loans
Community Development Financial Institutions (CDFIs) are mission-driven lenders that serve underbanked communities at fair rates. They offer personal loans, small business loans, and credit-building products specifically for people excluded by mainstream banks. Find CDFIs at CDFIFund.gov.
✅ Your Action Plan
- Build a $500 emergency fund first. Open a high-yield savings account (many pay 4–5% APY in 2026) and auto-transfer even $10/week. A $500 cushion eliminates most payday-loan triggers.
- Join a credit union. Credit unions are member-owned nonprofits that offer lower-rate loans and PALs. Membership is often open by employer, geography, or community group.
- Call 211 before taking a payday loan. Local emergency resources may cover the exact bill that is driving the borrowing need.
- Start a Roth IRA. Once the emergency fund is in place, open a Roth IRA at Fidelity or Vanguard (no minimum) and invest monthly — even $25. You are building the compound growth that payday loans steal.
- Know your rights. The CFPB’s payday loan rules give you the right to demand lenders verify your ability to repay. File complaints at consumerfinance.gov/complaint.
References
Center for Responsible Lending. (2023). Payday and car title lenders drain $9 billion per year from vulnerable communities. responsiblelending.org
Consumer Financial Protection Bureau. (2024). What is a payday loan? Consumer Help. consumerfinance.gov
Consumer Financial Protection Bureau. (2024). Consumer Financial Protection Bureau 2024 consumer credit card market report. consumerfinance.gov
Federal Deposit Insurance Corporation. (2022). 2021 FDIC national survey of unbanked and underbanked households. fdic.gov
National Credit Union Administration. (2024). Payday alternative loans. ncua.gov
U.S. Department of the Treasury, CDFI Fund. (2024). Community Development Financial Institutions Fund. cdfifund.gov
Methodology: APR calculations based on CFPB-documented payday loan fee structures. Compound growth projections use monthly compounding at stated annual rates. Historical S&P 500 average from S&P Dow Jones Indices. This article is for educational purposes and does not constitute financial advice.
📱 Stay Connected
Related Interactive Tracker
Live Settlement Tracker: Consumer Claims & Restitution
Find verified class action settlement claim forms, restitution deadlines, and payout eligibility.

Kemetic Minds Editorial Desk
Verified NewsroomPrimary-sourced investigative intelligence on civil rights, voting rights, federal policy, and consumer protection. Sourced from primary legal filings, government statistics, and direct field reporting.