Kemetic Minds — Financial Justice Series | June 27, 2026
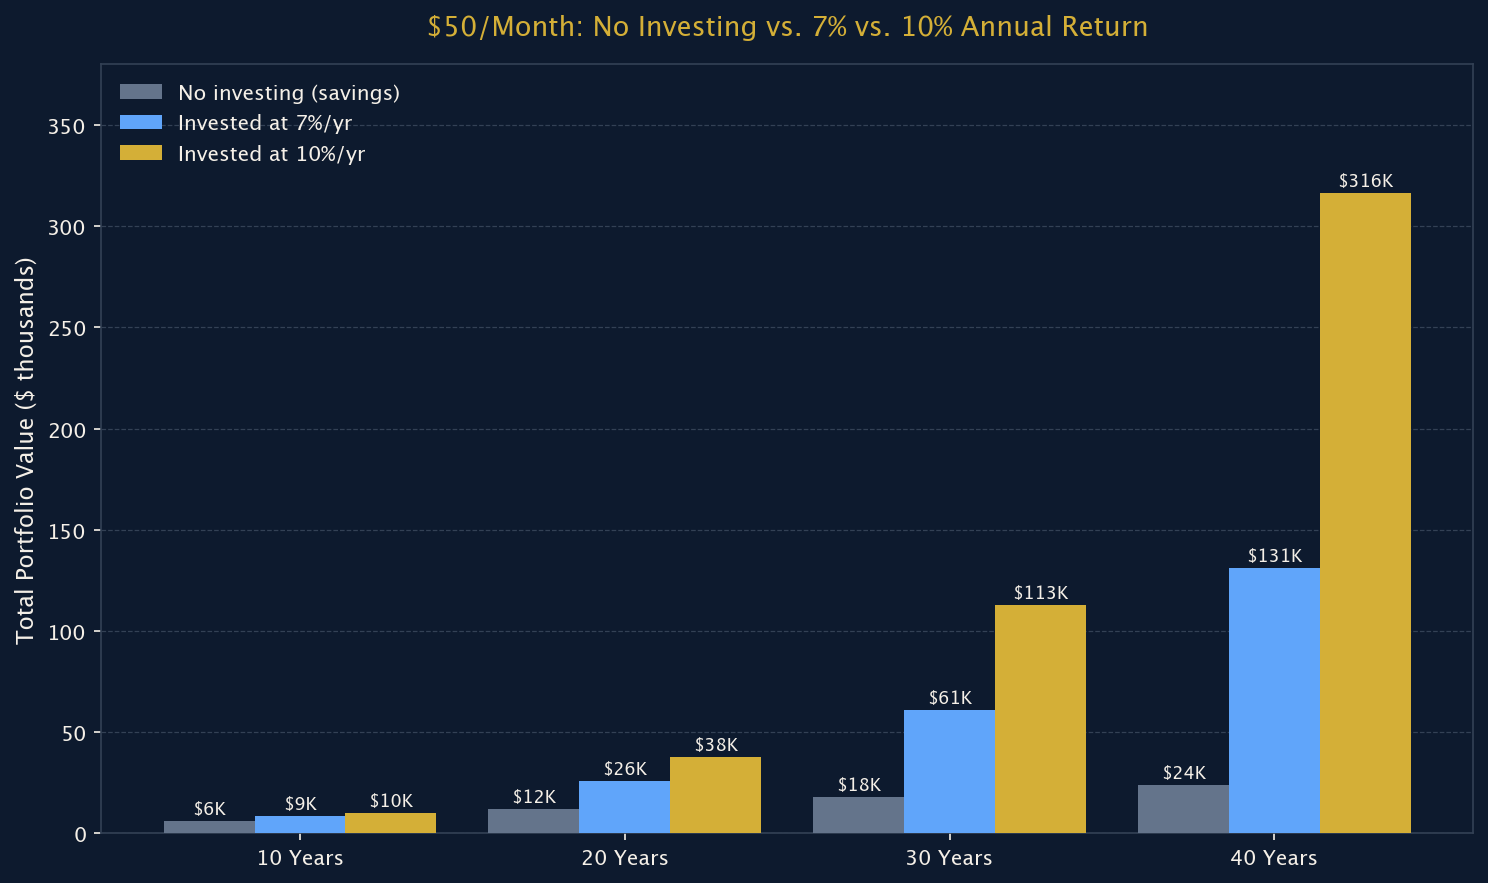
💰 What $50/Month Becomes (at 10%/yr)
- 10 years: $10,242
- 20 years: $37,968
- 30 years: $113,024
- 40 years: $316,203
Monthly compounding at 10% annual return (historical S&P 500 average). You do not need to pick stocks. You do not need a financial advisor. You need a Roth IRA, $50/month, and one low-cost index fund.
The One Thing the Wealthy Do That Most People Don’t
The fundamental secret of American wealth accumulation is not a secret at all. It is compound growth over time in the stock market. Warren Buffett made 99% of his wealth after age 65 — not because he became dramatically smarter, but because he started early and let decades of compounding work (Schroeder, 2008). The same math is available to anyone.
The Federal Reserve’s 2022 Survey of Consumer Finances shows that 61% of white families participate in the stock market in some form, versus only 34% of Black families. That 27-percentage-point gap in participation is one of the single largest contributors to the racial wealth gap. Every year in the market that a Black family misses is a year of compound growth lost — and once lost, those years cannot be recovered.
This guide is designed to get you started today. No prior knowledge required. No minimum balance needed.
Figure 1
$50/Month: No Investing vs. 7% vs. 10% Annual Return Over Time
Step 1: Open a Roth IRA (Not a Taxable Account)
The most important decision you will make as a beginning investor is where to invest, not what to invest in. A Roth IRA is the single best account for most beginning investors because:
- Your money grows 100% tax-free. You pay taxes on the money before it goes in (after-tax dollars). After that, every dollar of growth — including dividends and capital gains — is yours, tax-free, forever.
- No minimum to open. Fidelity and Schwab both allow you to open a Roth IRA with $0. Vanguard requires $1,000 minimum for some funds but $1 for ETFs.
- $7,000 annual contribution limit (2025–2026 for those under 50). Most beginning investors will not hit this limit. Just contribute what you can.
- You can withdraw your contributions (not earnings) at any time without penalty. This makes it more flexible than many people think.
📱 How to Open a Roth IRA in 15 Minutes
- Go to Fidelity.com, Schwab.com, or Vanguard.com.
- Click “Open an Account” → “Roth IRA.”
- Provide your Social Security number, address, and employment information.
- Link your bank account for transfers.
- Fund it — even $50 to start — and set up a monthly auto-transfer.
Step 2: Buy One ETF and Leave It Alone
You do not need to pick individual stocks. Research consistently shows that most professional fund managers fail to beat a simple index fund over 15 years — the S&P Dow Jones SPIVA Scorecard shows that over 90% of active large-cap fund managers underperform their benchmark index over 15-year periods (S&P Dow Jones Indices, 2024).
An index fund ETF buys a small slice of every stock in a particular index — like the S&P 500 (the 500 largest U.S. companies) or the total U.S. stock market. When the overall economy grows, your investment grows with it. You pay almost nothing in fees.
Figure 2
ETF Annual Expense Ratio Comparison (2025)
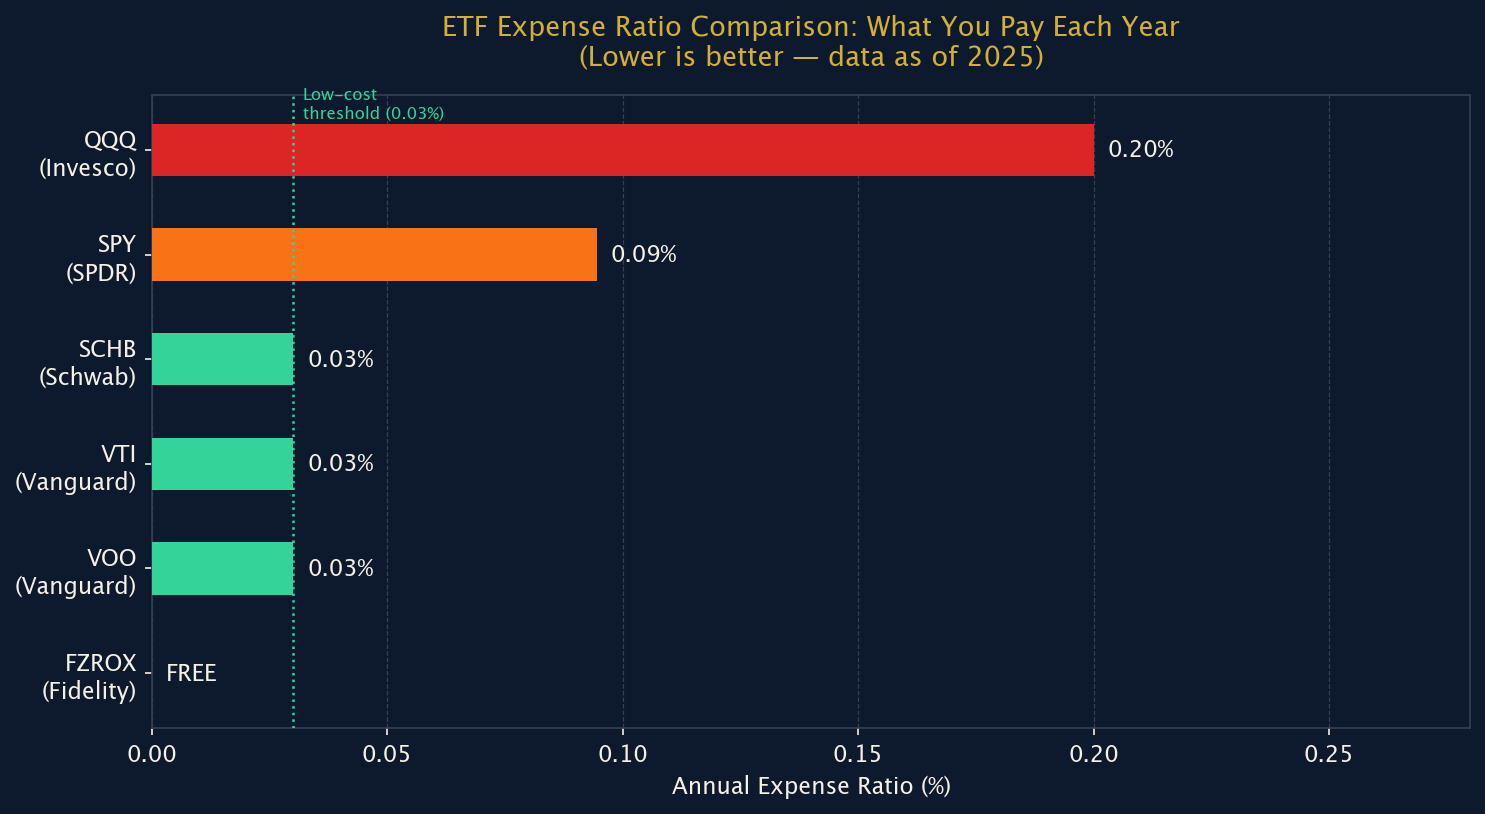
For most beginning investors, the choice is simple: FZROX (free at Fidelity) or VOO or VTI (0.03% at Vanguard or most brokerages). These three funds collectively hold over $2 trillion in assets and have nearly identical long-term performance.
Avoid: Any fund with fees above 0.5% per year. A 1% annual fee on $100,000 over 30 years costs you approximately $100,000 in lost compound returns compared to a 0.03% fund. The fees are not a small difference — they are a retirement’s worth of difference.
Step 3: Automate and Ignore the News
Set up an automatic monthly transfer of whatever you can afford — $25, $50, $100 — from your bank account into your Roth IRA on the day after your paycheck arrives. Then invest that amount in your chosen ETF on the same day (many brokerages allow automatic investing).
Then do not check it constantly. The stock market will have bad years. In 2022, the S&P 500 fell 18%. In 2020, it fell 34% in 33 days. In every case, it recovered and reached new highs. The strategy that consistently produces the best long-term returns is to invest regularly and not sell during downturns (Dalbar, 2024).
Dalbar’s annual quantitative analysis of investor behavior consistently finds that the average investor significantly underperforms the index they are investing in — because they sell during downturns and buy after rallies. The solution: automate your contributions and check your balance no more than once a quarter.
✅ Your Starter Investment Plan
- Open a Roth IRA at Fidelity, Schwab, or Vanguard today. Zero minimums at Fidelity and Schwab. Takes 15 minutes.
- Set a recurring monthly transfer for whatever you can afford — even $25 is a start.
- Buy one ETF: FZROX (free), VOO (0.03%), or VTI (0.03%). Select “dividend reinvestment” to automatically reinvest any dividends.
- If your employer offers a 401(k) match, contribute at least enough to get the full match before funding your IRA. A match is a guaranteed 50%–100% return that no investment can beat.
- Build an emergency fund of 3–6 months expenses in a high-yield savings account (4–5% APY in 2026) before investing aggressively. This prevents you from being forced to sell investments during a market downturn.
- Increase your contribution by 1% of your income every year, or every time you get a raise. You will not miss what you never had — and the compounding effect is enormous over decades.
References
Bhutta, N., Blair, J., Dettling, L., & Moore, K. B. (2023). Changes in U.S. family finances from 2019 to 2022: Evidence from the Survey of Consumer Finances. Federal Reserve Bulletin. federalreserve.gov
Dalbar. (2024). Quantitative analysis of investor behavior 2024. dalbar.com
S&P Dow Jones Indices. (2024). SPIVA U.S. scorecard year-end 2023. spglobal.com
Schroeder, A. (2008). The snowball: Warren Buffett and the business of life. Bantam Books.
Internal Revenue Service. (2025). Roth IRAs. irs.gov
Vanguard. (2025). Vanguard S&P 500 ETF (VOO). investor.vanguard.com
Methodology: Compound growth projections use the future value of annuity formula with monthly compounding at stated annual rates. Historical S&P 500 average return approximately 10% nominal, 7% real (inflation-adjusted), per S&P Dow Jones Indices. Expense ratios current as of 2025 fund prospectuses. Past performance does not guarantee future results. This is for educational purposes only, not personalized investment advice.
📱 Stay Connected

Kemetic Minds Editorial Desk
Verified NewsroomPrimary-sourced investigative intelligence on civil rights, voting rights, federal policy, and consumer protection. Sourced from primary legal filings, government statistics, and direct field reporting.